What is the scope and market size of the E-Fuels Market?
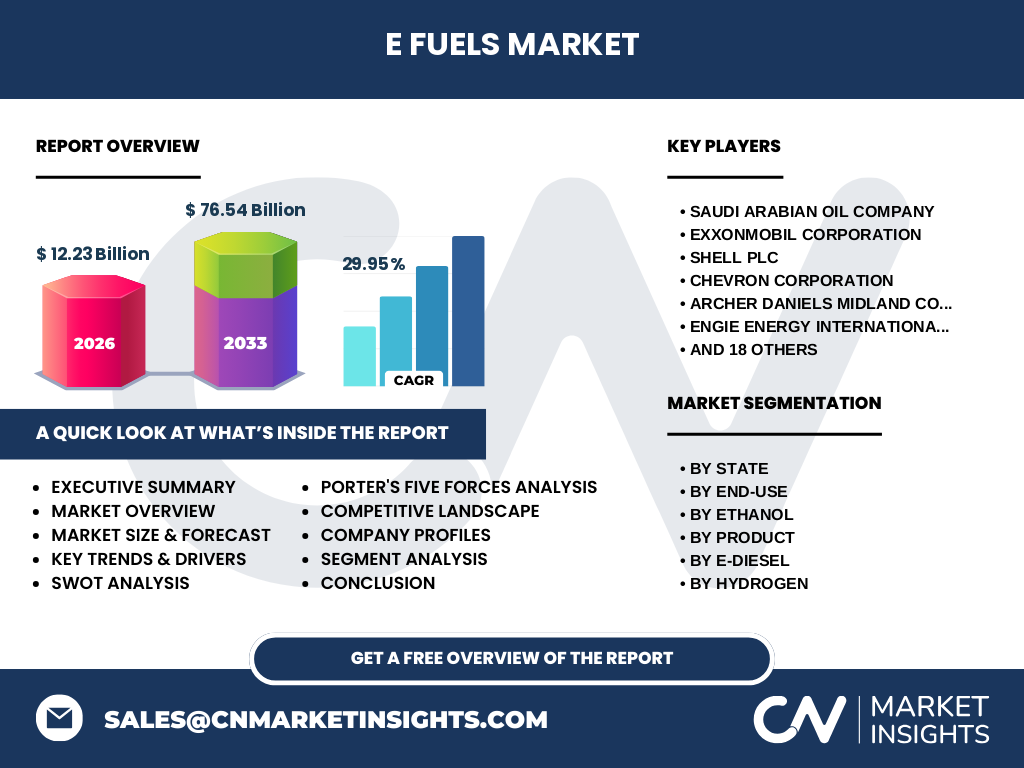
Our analysis indicates that the E-Fuels Market represents a transformative sector valued at 12.23 Billion in 2026. This industry encompasses sustainable synthetic alternatives derived from green hydrogen and captured carbon, critical for decarbonizing hard-to-abate sectors like marine and aviation through advanced Fischer-Tropsch and Reverse-Water-Gas-Shift technologies.
Key market drivers, restraints, challenges, and opportunities shaping the E-Fuels Market
The market is propelled by stringent European Union blending mandates and International Maritime Organization decarbonization targets. However, high capital expenditures for electrolyzers and scarce renewable electricity remain persistent constraints. Commercial opportunities lie in scaling Power-to-X infrastructure across major industrial hubs.
Emerging trends and growth patterns in the E-Fuels Market
The sector is witnessing a distinct pivot toward localized, modular production units situated near major industrial ports. Strategic collaborations between carbon capture pioneers like Climeworks AG and energy giants such as Shell plc are accelerating synthetic fuel commercialization and driving down per-barrel production costs.
COVID-19 impact analysis and recovery trajectory for the E-Fuels Market
While pandemic-related supply chain disruptions temporarily stalled capital deployment, the post-recovery trajectory for the E-Fuels Market industry trends has been exceptionally robust. Government green recovery packages injected vital liquidity into green hydrogen projects, accelerating pilot plants into commercial-scale operations.
Competitive landscape and strategic market concentration
The competitive ecosystem is characterized by joint ventures between traditional oil conglomerates like Saudi Arabian Oil Company and specialized innovators such as INERATEC GmbH. Market concentration is moderately high in technological IP, though traditional refiners leverage existing distribution networks to maintain dominance.
Executive summary of key findings for the E-Fuels Market
Our research confirms a monumental growth phase ahead, driven by net-zero commitments. The E-Fuels Market is poised for explosive expansion, transitioning from niche pilot plants to industrial-scale production supported by regulatory mandates and heavy corporate investments.
Market forecast and projected growth trajectory from 2027 to 2033
Based on our comprehensive forecasting models, the market is projected to skyrocket from 2027 to 2033, reaching an astonishing 76.54 Billion by the end of the forecast period. This trajectory represents a stellar CAGR of 29.95%, fueled by accelerating global decarbonization mandates.
Segmentation analysis across state, end-use, ethanol, product, and technology categories
Our segmentation breaks down the market into liquid and gas states, alongside diverse end-uses spanning automotive, marine, and aviation. Product categories feature E-Diesel, E-Gasoline, Ethanol, Hydrogen, E-Kerosene, E-Methane, and E-Methanol. Technological deployment relies heavily on Hydrogen Technology, Fischer-Tropsch, and Reverse-Water-Gas-Shift processes.
Regional market analysis and geographic performance distribution
Geographic performance shows Europe leading adoption due to aggressive RED II directives, followed by North America where federal tax credits stimulate massive green hydrogen investments. The Asia-Pacific region is emerging as a critical manufacturing hub for electrolyzers and synthetic fuel components.
In-depth regional review of key geographic markets
Europe maintains its regulatory edge, with Germany and the Netherlands serving as primary demand centers for Sustainable Aviation Fuel. Meanwhile, the Middle East leverages abundant solar resources and projects by NEOM Green Hydrogen Company to position itself as a dominant net exporter.
Company profiles and strategic positioning of leading market participants
Industry leaders are strategically positioning themselves through targeted acquisitions and greenfield developments. Entities like Porsche AG focus on automotive applications, while Neste Oyj and Shell plc concentrate on scaling Sustainable Aviation Fuel to meet pressing airline compliance deadlines.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants remains moderate due to steep capital expenditure requirements for electrolysis and carbon capture units. Bargaining power of suppliers is high for specialized catalyst manufacturers, while substitution threat from direct battery electrification is pronounced in light-duty automotive segments.
SWOT analysis highlighting strengths, weaknesses, opportunities, and threats
Strengths include drop-in compatibility with existing combustion infrastructure. Weaknesses involve high energy conversion losses. Opportunities emerge in maritime bunkering hubs, while threats stem from uncertain regulatory timelines and volatile renewable electricity feedstock costs.
Value chain analysis from raw materials to end-users
The value chain initiates with renewable power generation and direct air capture of carbon dioxide or biomass sourcing. This transitions through catalytic synthesis technologies managed by firms like Sunfire GmbH, culminating in distribution logistics managed by terminal operators like Mabanaft GmbH & Co.KG.
Investment insights and high-potential areas for capital allocation
Investors should direct capital toward synthetic kerosene production facilities and modular Fischer-Tropsch technology providers. High-potential areas include integrated green hydrogen-to-e-methanol plants situated near major international shipping ports to capture immediate marine bunkering demand.
Conclusion and key takeaways for stakeholders
The E-Fuels Market represents an indispensable pillar of the global net-zero transition. Stakeholders must forge cross-sector partnerships—combining renewable energy developers, engineering firms, and end-users—to de-risk capital-intensive projects and capture surging demand.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with C-suite executives across top companies, and secondary macroeconomic indicators regarding renewable energy capacity additions and regulatory compliance costs.
Scope of the report and coverage parameters
This report covers global production, distribution, and end-use demand dynamics for synthetic fuels through 2033. Limitations include potential delays in policy enforcement across emerging economies and unpredictable fluctuations in localized green electricity generation costs.
Recent developments in company announcements, product launches, and strategic partnerships
Recent market milestones include landmark off-take agreements signed between aviation leaders and sustainable fuel developers, alongside massive electrolyzer deployment announcements by Siemens Energy AG and strategic equity investments in direct air capture startups.